

Today’s Stock Picks are Home Depot and Sable Offshore. Both stocks are way down from their highs. Home Depot is down over 100 points since February when it traded above $385. And Sable sold for $33.00 in May of 2025.
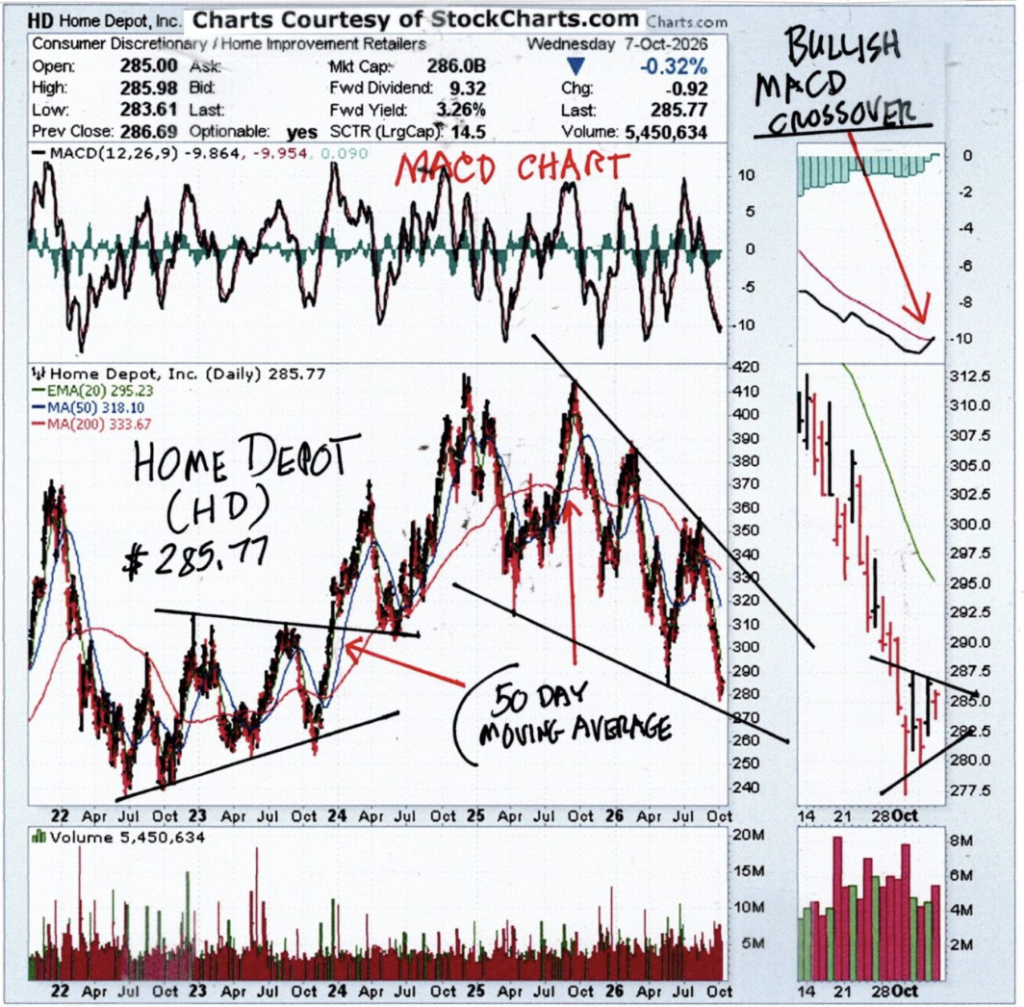
Home Depot (HD) closed at $285.77 Wednesday, and we think it’s cheap at this level, and we would be buying it using the Normal Buying Strategy outlined in our Market Letter – which is “Buy 30% of a stock Now, and buy 30% more on each 20% decline from your original buy price.”
If you had $10,000 to invest, that would mean buying $4000 of the stock now at $285.77, and Buying $3000 more at $228.62 and buying $3000 at $171.47…which we don’t think will ever happen. The
lowest price HD sold for in the last 5 years was about $240 in June of 2022. So using this strategy almost always insures great average prices, ergo, you make money.
Per Finviz, Melius Research initiated coverage on HD with a Buy Rating on October 6 th . Wolfe Research downgraded it on June 23 rd from Out-perform to Peer Perform, and On May 20 th , Telsey Advisory reiterated their Outperform Rating, and lowered the Target Price from $435 to $430. Per Finviz, the company has 998.00 Million shares outstanding, and 10.57 Million shares are short. Current earnings are $14.29 per share and next year’s earnings are estimated at $15.95. The current PE Ratio is 20.00 and the forward 12 months PE is projected at 17.91. It has a
3.25% Dividend Yield.
You can see by the 5-Year chart, that it’s trading at a generally low historic price. Also the Zoom chart on the right shows it is making a small consolidation triangle, which we think it will rally upward from, shortly. We like the stock.
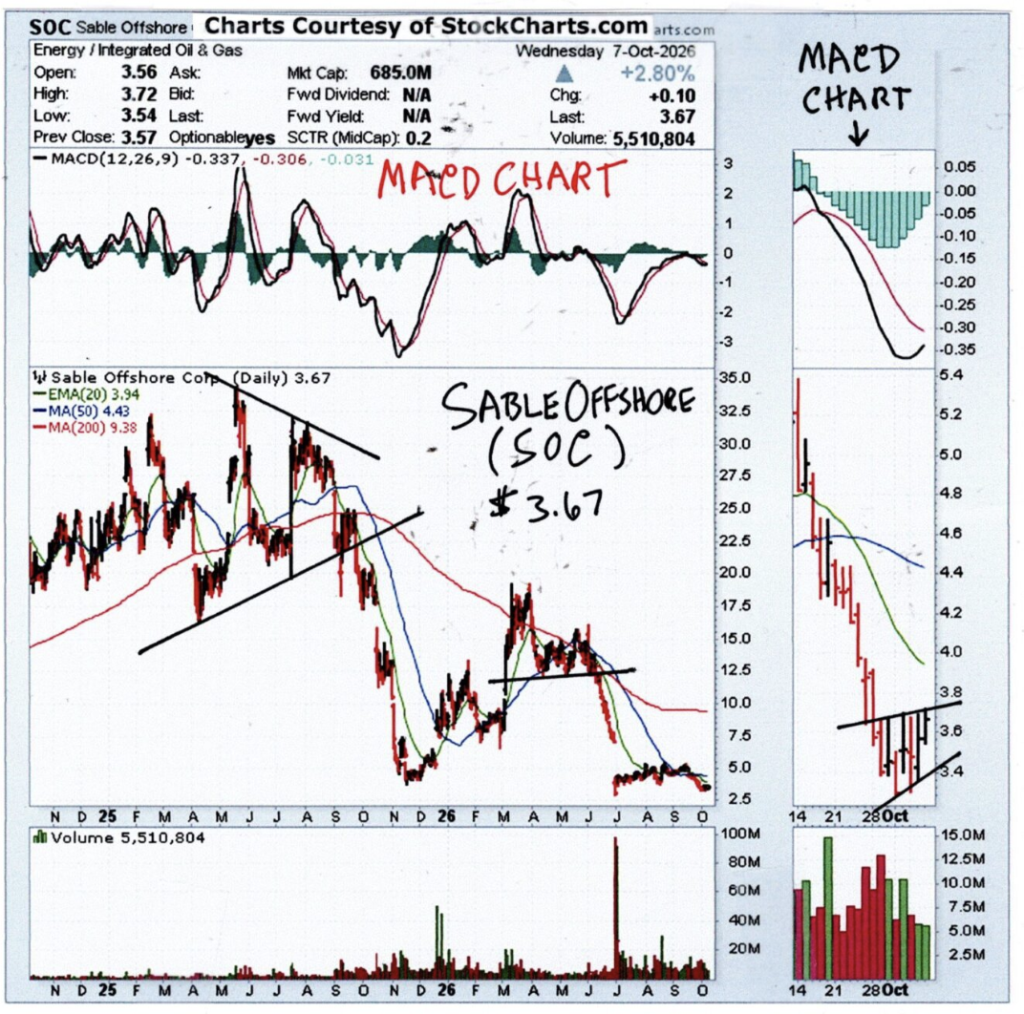
The next stock, Sable Offshore Corp (SOC) closed Wednesday at $3.67.
It engages in offshore oil and gas field operations in federal waters off of California. The shares have sold off on the company’s production and cash flow delays, but apparently, the company is soon to see production from three platforms…read the details at Finviz.com under News: Sept.28-26 “Sable Offshore Corp. provides Operational Update”.
On October 5, William Blair initiated coverage with an Outperform Rating. And on October 2 nd , J.P. Morgan gave it an Overweight rating with a $10 Target Price.
Per Finviz.com, the company has 191.87 million shares outstanding and 46.65 Million shares are Short, which gives it a Short Float of 27.49%, a very high number, which makes it a good candidate for a Short Squeeze. The company shows current earnings of minus $-3.33 per share, but next year’s earnings are estimated at $.84 per share. The current PE Ratio is nil, but the company’s estimated 12 Month’s forward PE Ratio is a low 4.38. There was Significant Insider Selling back in March and April of this year at prices ranging from 13.33 to 16.69, but
none since.
If you look at the 2-Year Chart, you can see that it’s only selling at a fraction (about 11%) of its previous $33 value in May of 2025. I looks like it’s about to have a Bullish MACD Crossover in the Zoom chart on the right, and also making a small consolidation which we think will be the bottom for the stock. We like the company, and at this point we don’t see any downside for the stock, only upside. If they get their production renewed, we think the stock could double within 90 days,
and possibly triple within 6 months, assuming we don’t get into a Bear Market in the interim.
This article is not investment advice and it is not in any way to be construed as investment advice. For investment advice consult a registered investment advisor or a certified financial planner. Joe Cotton’s website is www.cottonstocks.net.
Returning as a columnist for the NKyTribune, Cotton is publisher of the market newsletter, Cotton’s Technically Speaking. He is a graduate of Xavier University, a former bank manager and credit analyst, and a former Fidelity Investments registered investment representative. Contact him at cottonstocks@hotmail.com